Why Property Management Firms Struggle with Month-End Close and How to Fix It Fast
- October 15, 2026
- Tajinder Malhotra
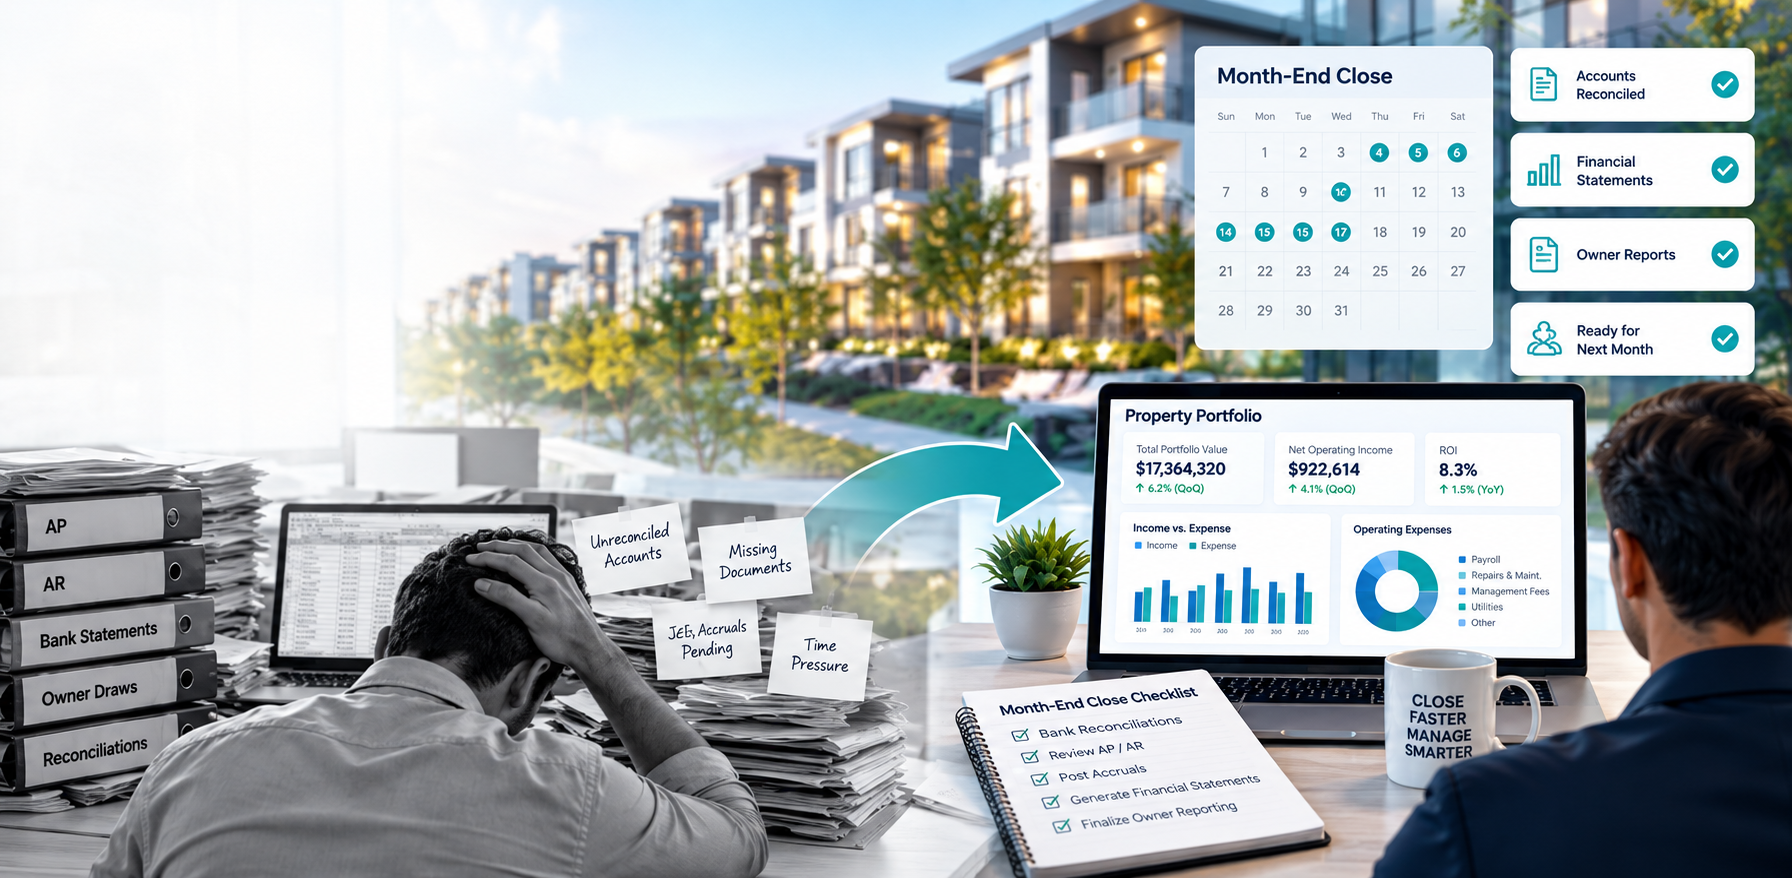
Property management firms struggle with month-end close because of missing invoices, incomplete reconciliations, high transaction volume, inconsistent property-level accounting, and manual processes. A standardized checklist, a fixed closing calendar, and continuous reconciliation shorten the close and improve owner reporting accuracy.
A late month-end close costs more than time. Owner reports slip. Property performance data goes stale before anyone reads it. Variance analysis waits. Controllers absorb the pressure while CFOs make decisions on numbers that are already a week old.
This problem compounds with growth. More properties mean more entities, more transactions, and more reconciliation points. A portfolio that closed in five days at twenty properties can take fifteen at sixty not because the team got worse, but because the process never scaled with it.
This article breaks down why month-end close slows down in property management accounting, and what firms can do to close faster without cutting corners on accuracy.
Month-end close is the process of finalizing a property’s financial records for the month posting every transaction, reconciling every account, and producing accurate financial statements before reports go to owners and decision-makers.
For property management firms, this process includes:
Accurate, timely closing matters because every downstream decision depends on it. Owners rely on it to judge property performance. Controllers rely on it to catch errors before they compound. CFOs rely on it for portfolio-wide visibility. Asset managers rely on it to time renovations, refinancing, and dispositions. A slow close delays all four.
Read more: – Month-End Close Checklist Every Property Management
Vendors submit invoices late. Property managers sit on paper receipts. Utility bills arrive after the close window has already shut. The result: expenses land in the wrong month, net operating income looks inflated, and owners see numbers that don’t match reality.
The fix starts with accrual discipline recording known, unbilled expenses even before the invoice arrives, based on historical patterns and vendor contracts.
Unreconciled transactions pile up. Stale items sit untouched for months. Review procedures vary from one accountant to the next, so nobody catches the gap until an owner questions a number.
Reconciliation isn’t a month-end task. It’s a standing discipline. Firms that treat it as a once-a-month scramble will always close late.
Rent receipts. Vendor payments. Security deposits. Utility charges. Maintenance invoices. Inter-entity transfers. Multiply that across forty, sixty, or a hundred properties, and transaction volume alone becomes the bottleneck — regardless of how skilled the team is.
Volume doesn’t shrink. Process capacity has to grow to match it.
One property codes repairs to maintenance expense. Another books the same cost to capital improvements. One entity closes receivables on the 25th; another waits until the 1st. These inconsistencies make portfolio-wide reporting unreliable and force Controllers to manually reconcile differences that shouldn’t exist.
Standardized account mapping and consistent cutoff procedures fix this at the source — not after the fact.
Accounting can’t close what it doesn’t have. Missing approvals, delayed lease documentation, and unclear ownership between site teams and the accounting department stall the process long before a journal entry gets posted.
This isn’t a systems problem. It’s a communication and accountability gap between the people closest to the property and the people closing the books.
Duplicate data entry. Spreadsheet formula errors. Manual journal entries with no audit trail. Limited visibility into which tasks are done and which are still outstanding. Disconnected systems force accountants to reconcile data instead of analyzing it.
Automation helps here — but only when paired with clear review steps. A faster error is still an error.
Overloaded accountants manage too many properties with too little review capacity. Turnover resets institutional knowledge. Nobody owns the close calendar, so deadlines slide without consequence.
Clear ownership — one person accountable for each task, one person accountable for the whole close — closes this gap fast.
Build a checklist with recurring tasks, assigned owners, due dates, dependencies, and reviewer sign-offs. A checklist turns a chaotic scramble into a repeatable, trackable process.
Fix a schedule for invoice submission, transaction posting, reconciliations, journal entries, reviews, and financial statement delivery. Property managers and accountants both need to know the deadlines and know that they hold.
Reconcile bank accounts, clearing accounts, receivables, payables, and intercompany balances continuously. Waiting until month-end to start reconciling guarantees a slow close.
Set firm invoice submission deadlines. Build clear approval workflows. Use recurring accrual schedules for known, predictable expenses. Document the basis for every accrual so reviewers can validate it quickly.
Apply a consistent chart of accounts, consistent property coding, and consistent accounting policies across every entity in the portfolio. Document journal-entry support requirements and apply the same review standard everywhere.
Accounting software, bank feeds, invoice workflows, and reconciliation tools reduce manual entry and catch errors earlier. Automation accelerates the process — it doesn’t replace review, exception handling, or internal controls.
Measuring the close process reveals where it breaks down.
| Metric | What It Measures | Why It Matters | Example Target or Review Approach |
| Days to close | Total time from month-end to final reports | Shows overall process efficiency | Review monthly; benchmark against prior periods |
| % of reconciliations completed on time | Reconciliation discipline throughout the month | Prevents month-end backlogs | Track weekly, not just at close |
| Number of post-close adjustments | Accuracy of the original close | High counts signal upstream process gaps | Review trend over multiple periods |
| Unresolved reconciling items | Outstanding items aging past 30/60/90 days | Flags control weaknesses | Investigate anything aging past one cycle |
| On-time financial report delivery | Whether owners receive reports on schedule | Direct measure of owner satisfaction | Track against the published calendar |
These are illustrative benchmarks, not universal standards. Every firm should set targets based on portfolio size, reporting obligations, system capabilities, and staffing levels.
This schedule illustrates one approach. Some portfolios close faster; complex, multi-entity portfolios may need more time.
| Timeframe | Activity |
| Days 1–2 | Complete transaction posting and invoice cutoff |
| Days 2–4 | Finalize accruals and key reconciliations |
| Days 4–6 | Review journal entries and balance sheet accounts |
| Days 6–8 | Analyze property-level variances and resolve exceptions |
| Days 8–10 | Complete Controller review and issue financial reports |
Read more: – Month-End Closing Process
Some signs point clearly toward outside support:
Firms in this position often outsource property management back office services to stabilize transaction processing, accounts payable, reconciliations, general ledger maintenance, accrual preparation, and financial reporting support. The exact scope always depends on the service agreement and the client’s internal controls — outsourcing supplements the process, it doesn’t replace management oversight.
Multifamily portfolios carry their own complexity: unit-level revenue tracking, utility reimbursements, tenant turnover costs, and entity-level reporting for multiple ownership structures. Multifamily accounting services built for this environment standardize workflows across properties, maintain consistent accounting schedules, and clear reconciliation backlogs that have been building for months.
Strong outsourcing services for property manager operations depend on secure data access, documented procedures, segregation of duties, clear review responsibilities, and strict data confidentiality. The accounting partner works alongside the Controller — not in place of them. Outsourcing standardizes execution. It does not remove management accountability, and it does not guarantee a faster close on its own. The firm’s internal discipline still sets the ceiling.
A fast, accurate month-end close isn’t an accident. It’s the product of a standardized checklist, a fixed closing calendar, continuous reconciliation, and clear ownership at every step. Firms that build this discipline stop reacting to the close and start controlling it.
For property management firms facing persistent close delays, reconciliation backlogs, or a portfolio growing faster than the accounting team, Outsourcing Hub India supports recurring accounting and back-office workloads transaction processing, accounts payable, reconciliations, and financial reporting support included. Explore OHI’s property management firms services or get in touch to discuss where your close process is losing time.
Month-end close takes longer when invoices arrive late, reconciliations fall behind, properties use inconsistent accounting processes, and teams rely on manual spreadsheets. Portfolio growth without added process capacity makes every one of these issues worse.
There’s no single standard — timelines depend on portfolio size, system capabilities, and staffing. A 10-day close is a common illustrative example, but simpler portfolios may close faster and complex, multi-entity portfolios often need more time.
A complete checklist includes income postings, invoice cutoff, accruals, bank and balance sheet reconciliations, receivable and payable reviews, intercompany reconciliations, variance analysis, Controller sign-off, and final report distribution.
Standardizing the chart of accounts, reconciling continuously instead of only at month-end, enforcing invoice submission deadlines, and documenting accrual support all improve accuracy. Consistent property-level coding across the portfolio matters as much as any single technical fix.
Outsourcing becomes worth evaluating when the close is consistently late, reconciliation backlogs keep growing, the portfolio is outpacing the accounting team’s capacity, or Controllers lack time for review and analysis. Scope and oversight still depend on the client’s internal controls.