How Self-Managed HOAs Can Improve Financial Transparency on a Limited Budget
- October 30, 2026
- OHI
A self-managed HOA may have only a few board members handling nearly every financial responsibility for the community. One volunteer may be reviewing invoices, another may be tracking homeowner assessments, and the treasurer may be preparing financial reports while also trying to reconcile the bank account.
That arrangement can work, but it often creates one recurring problem: limited financial visibility.
When records are incomplete, reports are delayed, or expenses are not clearly categorized, homeowners may start asking where their assessment money is going. Board members may also find it difficult to determine whether the association is staying within budget, whether reserve balances are accurate, or whether overdue assessments are being followed up consistently.
Financial transparency helps solve these problems. It gives board members and homeowners a clearer view of the association’s financial position and creates greater accountability around spending decisions.
The good news is that improving financial transparency does not necessarily require expensive software, a large accounting team, or a full-service management company. For many small and self-managed HOAs, the biggest improvements come from better processes, consistent reporting, simple financial controls, and organized documentation.
Financial transparency means board members and homeowners can understand how association funds are collected, spent, and maintained.
For a self-managed HOA, this is especially important because homeowners often rely directly on volunteer board members for financial explanations. If the board cannot clearly explain a major expense or account balance, uncertainty can quickly turn into concern.
Good financial transparency can help an HOA:
Consider a simple example.
An HOA spends $12,000 on common-area repairs during one quarter. Homeowners notice the expense in a year-end summary but are not given any explanation about the work, vendor, or budget category.
Even if the expense was legitimate, unclear reporting may create unnecessary questions.
A more transparent approach would show that the expenditure related to a specific maintenance project, identify whether it was planned or unexpected, and explain how it affected the operating budget or reserve balance.
Transparency is not about sharing every accounting detail with every homeowner. It is about making financial activity understandable and maintaining enough documentation to support the numbers being reported.
Most transparency problems do not begin with intentional mismanagement. They usually develop because volunteer board members have limited time and may not have professional accounting experience.
Common problems include:
Transactions may be recorded late or without enough description. Missing invoices, inconsistent expense categories, and unrecorded assessment payments make it difficult to understand the association’s actual financial position.
If financial reports are prepared several months late, the board is effectively making decisions using outdated information.
The accounting records may show one balance while the bank statement shows another. Without reconciliation, missing transactions, duplicate entries, outstanding checks, or bank charges may go unnoticed.
A roof repair, routine maintenance charge, reserve expense, and capital improvement should not automatically be treated the same way. Poor classification makes reports harder to interpret.
Boards may approve payments without maintaining the corresponding invoice, contract, proposal, or approval record.
When reserve expenditures and operating expenses are not clearly separated, homeowners may have difficulty understanding how much cash is available for day-to-day expenses versus future capital projects.
Even accurate financial reports can create confusion if homeowners rarely receive financial updates or if the information is presented without context.
These issues are common precisely because self-managed associations depend on volunteers. The solution is usually not to create a complicated accounting department. It is to make the financial process simpler and more consistent.
Every meaningful financial transaction should be recorded consistently.
That includes:
The general ledger should provide a clear history of these transactions.
Supporting documents matter just as much as the accounting entry itself. If the ledger shows a $3,800 plumbing expense, the board should be able to locate the corresponding invoice and approval.
A practical approach is to organize digital files by year, month, and document type.
For example:
2026 > March > Vendor Invoices
2026 > March > Bank Statements
2026 > March > Reconciliations
This simple structure can save considerable time during board reviews and year-end reporting.
Self-managed HOAs should review their finances monthly rather than waiting until the end of the year.
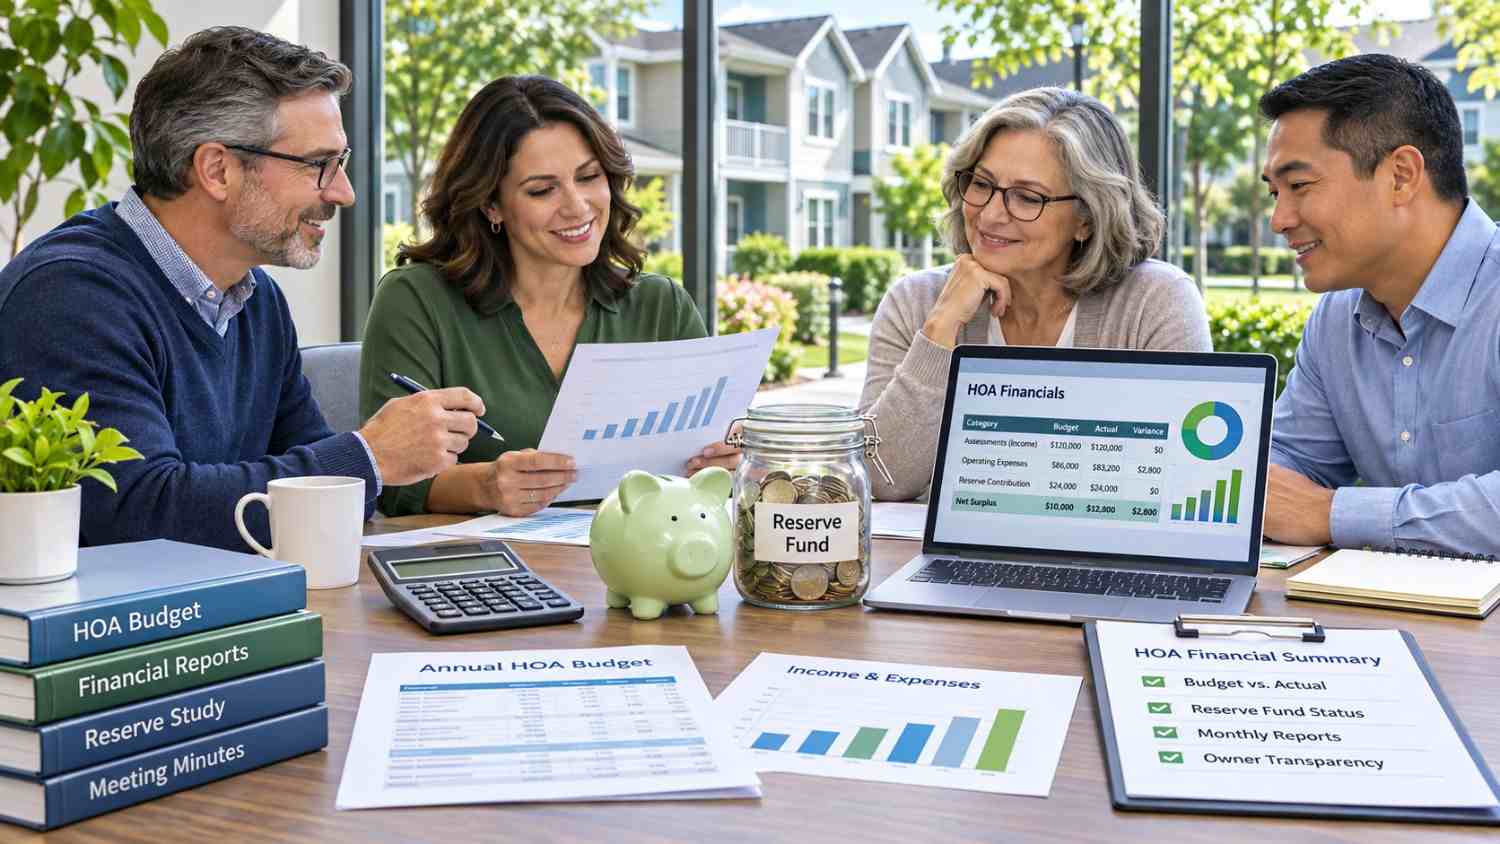
A basic monthly reporting package may include:
The balance sheet shows the association’s assets, liabilities, and fund balances.
The income and expense statement shows what the HOA collected and spent during the period.
The budget-versus-actual report helps identify areas where expenses differ from the approved budget.
For example, if the HOA budgets $2,500 per month for landscaping but actual costs have averaged $3,400 for three months, the board should understand why.
That variance may indicate a contract increase, additional seasonal work, or an accounting classification issue.
The earlier the board identifies the cause, the more time it has to respond.
Operating funds and reserve funds have different purposes and should be tracked clearly.
Operating funds generally cover recurring expenses such as:
Reserve funds generally support larger future repair and replacement needs.
The board should maintain clear records of:
Where appropriate under the association’s governing documents and applicable state requirements, separate bank accounts may help make the distinction clearer.
Mixing operating and reserve transactions can create misleading financial reports.
For example, if a major roof expenditure is recorded as an ordinary monthly operating expense, the association may appear dramatically over budget even though the project was planned and funded through reserves.
Bank reconciliation is one of the most useful financial controls an HOA can implement.
A bank reconciliation compares the balance in the accounting records with the balance shown by the bank.
The process can identify:
Suppose the accounting records show $85,000 in cash, while the bank statement shows $79,500.
The difference might be completely explainable because of outstanding payments. But until the accounts are reconciled, the board cannot confidently rely on the reported balance.
Monthly reconciliations keep these differences from accumulating.
For self-managed associations, having another board member review the completed reconciliation can provide an additional layer of oversight.
The annual budget should be more than a list of estimated expenses.
A useful budget should help board members and homeowners understand where association money is expected to go.
Common budget categories may include:
Historical spending can provide a useful starting point, but the board should also consider upcoming contracts, expected repairs, insurance renewals, and planned projects.
Once the budget is approved, actual spending should be compared with it regularly.
A budget-versus-actual review helps answer a simple question:
When significant differences occur, document the explanation.
This makes later financial discussions much easier.
Even a small association benefits from clear payment procedures.
A simple process may look like this:
The person preparing a payment should ideally not be the only person authorizing it.
Smaller associations may not be able to maintain perfect separation of duties, but some independent review is still better than none.
For example, if the treasurer prepares payments, the president or another authorized board member could review larger invoices before payment.
The goal is to create a visible approval trail.
Improving transparency does not require expensive enterprise software.
A small HOA may be able to use:
Spreadsheets can work well for simple tasks such as budget tracking or project monitoring.
However, they become harder to manage as transaction volume increases.
Multiple copies may circulate between board members, formulas can be changed accidentally, and version control can become difficult.
The board should choose tools based on the complexity of the association, not simply on price.
The best system is one that allows the HOA to record transactions accurately, store supporting documents, reconcile accounts, and produce consistent reports.
Financial transparency requires communication.
Boards can provide homeowners with appropriate updates through:
Detailed record access should follow the association’s governing documents and applicable laws.
A financial update does not need to include every ledger transaction.
Instead, it should answer the questions homeowners are most likely to have:
Plain-language explanations can be more useful than pages of accounting reports without context.
There comes a point when volunteer board members may spend so much time managing accounting tasks that self-management becomes less efficient.
Outside support can be useful when:
Professional hoa accounting services can support recurring work such as bookkeeping, bank reconciliations, financial statement preparation, accounts payable, assessment tracking, and budget reporting.
Working with experienced hoa accounting firms may also help boards establish more consistent accounting procedures and gain professional oversight without employing a full-time accountant.
For associations that need help with repetitive administrative work, Property Management Back-Office Services can support areas such as transaction processing, invoice administration, accounts payable workflows, financial data organization, and other routine back-office tasks.
Outsourcing does not remove the board’s responsibilities. The board still needs appropriate oversight, approval processes, access to financial records, and an understanding of the association’s financial position.
The value of professional support is often in creating more reliable processes while reducing the amount of routine accounting work handled by volunteers.
Strong financial controls do not always require sophisticated systems.
The following checklist can help a self-managed HOA strengthen accountability.
| Financial Control | Practical Purpose |
| Two-person review for significant payments | Reduces the risk of unauthorized or incorrect payments |
| Monthly bank reconciliations | Confirms bank activity matches accounting records |
| Documented payment approvals | Creates a clear financial trail |
| Separate operating and reserve tracking | Improves visibility into available funds |
| Regular assessment aging review | Identifies overdue homeowner balances |
| Secure invoice and statement storage | Preserves supporting documentation |
| Monthly financial report review | Helps identify problems early |
| Defined board responsibilities | Reduces confusion about who handles each task |
The exact controls will vary depending on the size and structure of the association.
What matters is consistency.
A simple process that the board follows every month is usually more effective than a complex policy that is rarely used.
Consider a hypothetical self-managed HOA with 80 residential units.
Three volunteer board members handle most of the association’s financial work.
Over time, several problems develop.
Monthly financial reports are often delayed because the treasurer prepares them only when time permits. Maintenance costs appear in several different expense categories. Some overdue homeowner assessments are tracked in a separate spreadsheet, while others are recorded in the accounting software.
The board also has difficulty confirming the current reserve balance because transfers and reserve-funded expenses are not consistently documented.
The association does not need to purchase a large management system to improve the situation.
It could begin with four changes.
First, the board reconciles every bank account monthly.
Second, it adopts a standardized monthly financial package showing the balance sheet, income and expense statement, budget-versus-actual results, assessment aging, and reserve balance.
Third, invoices and bank records are stored in a secure digital folder using the same naming structure every month.
Fourth, significant vendor payments require documented approval from two authorized board members.
Within this process, the board gains better visibility into cash, spending, overdue assessments, and reserves.
The improvement does not come from adding complexity. It comes from using the same financial process consistently.
Improving financial transparency does not have to be expensive or complicated for self-managed HOAs. Consistent bookkeeping, monthly financial reporting, bank reconciliations, clear budget tracking, and proper documentation can make a significant difference in how an association manages its finances.
The key is to establish simple financial processes that board members can follow consistently. When homeowners understand how assessments are collected, where money is spent, and how reserve funds are maintained, it becomes easier to build trust and make informed financial decisions.
However, as financial responsibilities grow, managing every accounting task internally can become challenging for volunteer board members. Working with experienced HOA accounting firms or using professional HOA accounting services can help maintain accurate records, improve financial reporting, and strengthen accountability without the expense of hiring a full-time accounting team.
For self-managed associations, the goal is not to spend more on financial management but to create better systems that make every dollar easier to track, explain, and manage.